Corporate year-end preparation is easier to discuss when the books and supporting documents tell the same story. You do not need to wait until the closing date to start organizing them. Separate work you can do beforehand from balances captured at year-end and documents that arrive afterward.
Key points
- Confirm the corporation's actual fiscal period and identify unfinished bookkeeping before assembling the package.
- Connect year-end reports and balances with their supporting records, and keep unresolved questions visible.
- Treat this as preparation for a scoped engagement, not a universal T2 attachment list.
Before year-end: confirm the period and find gaps
A corporation's tax year is its fiscal period. Do not assume it ends on December 31. Confirm the start and end dates with your records and preparer, particularly if this is the first return or the company has changed. Agree on when preliminary information and final reports should be available.
- Identify the last completed bookkeeping month. List unfinished periods, unreconciled accounts and transactions still needing an explanation so cleanup can be assessed before preparation starts.
- Gather sales invoices, purchase invoices, expense receipts and supporting agreements. Keep explanations of unusual transactions beside the relevant record rather than relying on a bank description alone.
- Locate the prior corporate return, financial information, notices of assessment or reassessment and relevant CRA correspondence. Identify tax instalments and other payments made during the period.
- Create a list of business bank accounts, credit cards, loans and payment processors. Include accounts closed during the year so activity is not missed.
- Collect documents for equipment or other asset purchases, sales and trade-ins, including dates, invoices, financing and proceeds. Flag changes in use for assessment rather than deciding the tax treatment yourself.
At year-end: capture balances and their support
Use the same reporting period across the bookkeeping package. The General Index of Financial Information, or GIFI, uses codes to report financial statement information to the CRA. That makes clear underlying financial information useful; it does not turn every item below into a filing attachment.
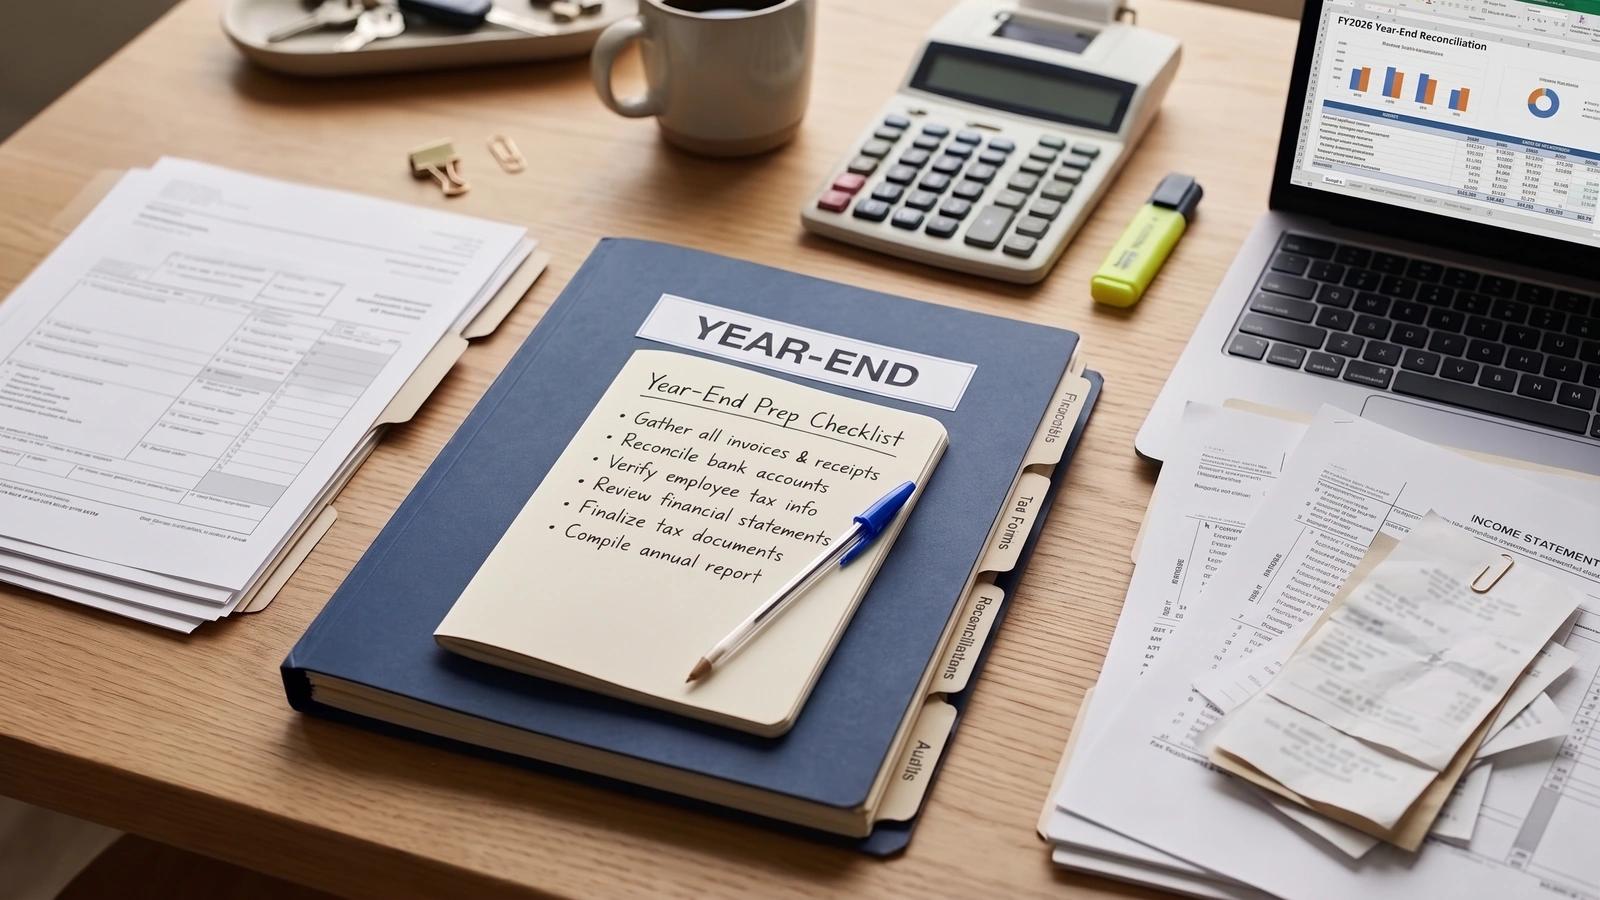
- Export the trial balance, general ledger, income statement and balance sheet available from the books. Label preliminary versions clearly and note any adjustments still outstanding.
- Prepare bank and credit-card reconciliations with statements supporting the closing balances. Include loan statements and identify unexplained differences instead of forcing the accounts to agree.
- List unpaid customer invoices and supplier bills at the closing date. Flag disputed balances, deposits, prepayments and invoices near year-end whose period needs clarification.
- If the business holds inventory, arrange to document quantities and supporting cost information around the closing date. Record the count date and movements between that date and year-end for discussion.
- If relevant, gather payroll summaries, remittance records and sales-tax returns and balances. Label each record's period so information from different reporting periods is not mistaken for a matching set.
Document company changes and owner transactions
Explain changes in business activities, addresses, ownership or shareholdings. Provide relevant existing agreements, resolutions or minutes through the agreed secure method. For money moving between the company and an owner, collect transaction details and supporting records, including reimbursements, advances and repayments. Identify what happened; do not guess whether an amount should be salary, a dividend, a loan or an expense.
Unusual transactions, ownership changes and reorganizations need separate assessment. This checklist does not provide shareholder advice, recommend a compensation approach or establish the legal or tax treatment of a company change.
After year-end: complete the handoff
Some closing statements and invoices arrive after the year ends. Add them to the package and identify which earlier reports they affect. Keep a short missing-item log showing the document, person responsible and next action. Send a clearly labelled replacement when a report changes, rather than leaving the preparer to choose between conflicting versions.
Use folders by record type and filenames showing the account and period. Retain the underlying records after handing over summaries. Corporate record-retention requirements vary, and some records must be kept longer than others; check before disposing of anything.
Confirm the preparation scope
Corporate Tax Returns is the relevant service for discussing T2 preparation. Monthly Bookkeeping may support ongoing records separately; historical cleanup also needs its own assessment. The related cleanup-versus-monthly-bookkeeping resource helps distinguish those needs, while the payroll checklist is useful when employee records form part of your package.
Preparation is not an audit, review engagement or assurance report. Tax planning and CRA representation are not automatically included. You review and approve the required information before filing-related steps proceed within the agreed scope. For an initial inquiry, describe the year-end, completed periods and open issues only. Do not send financial documents or account credentials through the general form; agree on secure sharing, authorizations, and filing and payment responsibilities separately.