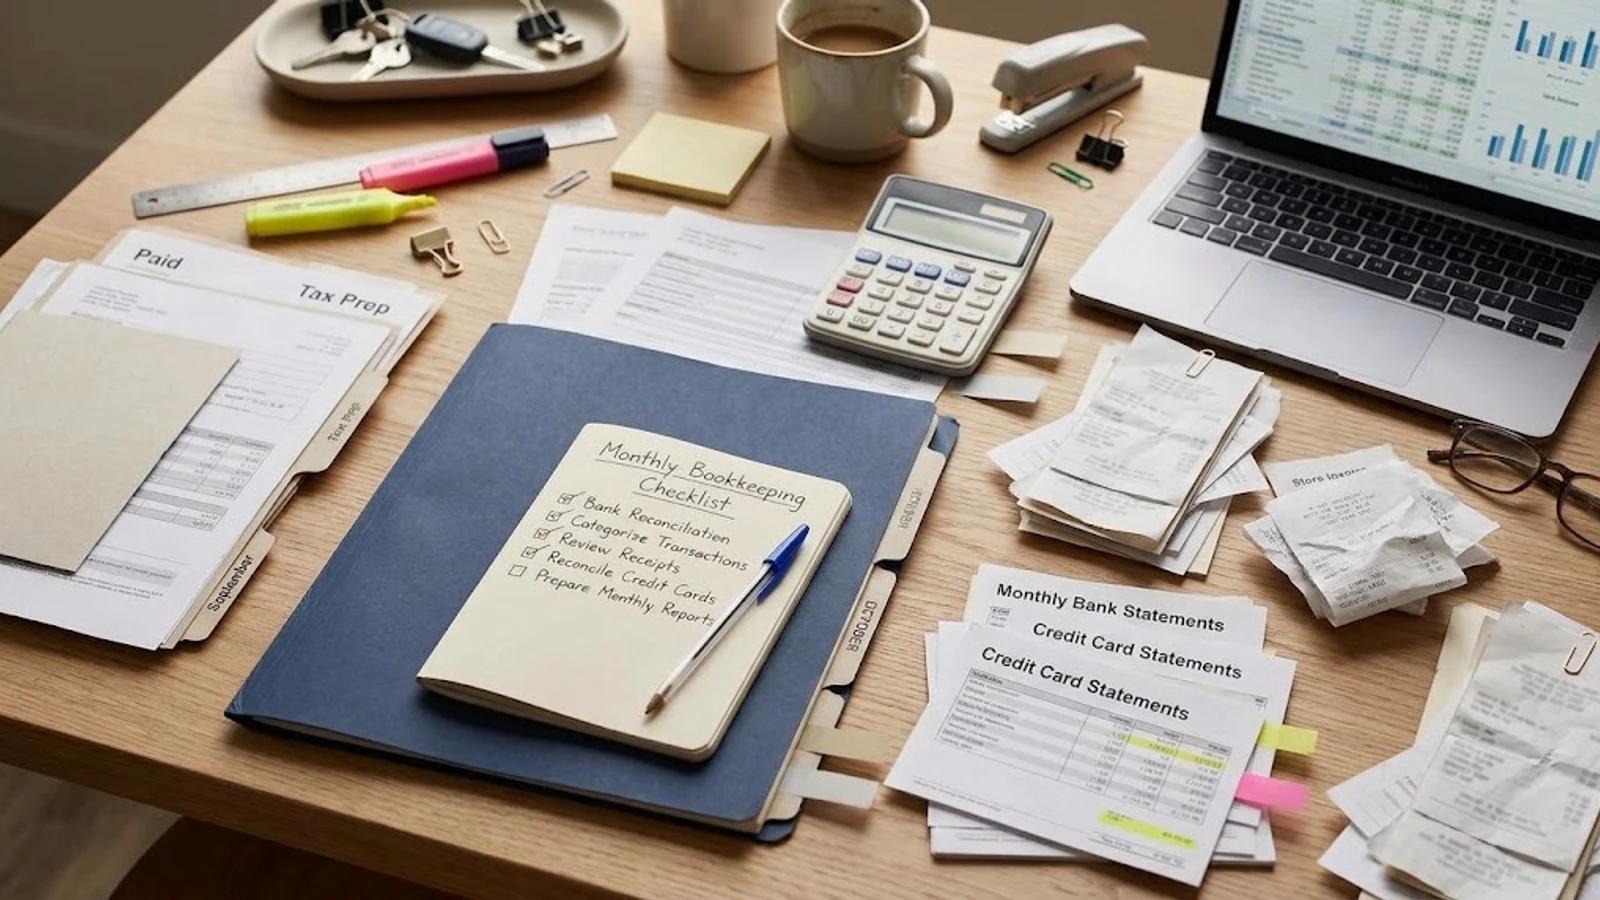
A useful monthly bookkeeping handoff brings together the records and explanations behind your business activity. Rather than sending an unexplained collection of receipts, aim to show what happened, which account was involved and what still needs an answer. The checklist below is a recommended starting point for Canadian small business owners, not a CRA-prescribed monthly submission package.
Key points
- Confirm the period, accounts and scope before gathering a suggested monthly records package.
- Keep supporting documents and transaction explanations connected to the bookkeeping entries.
- Flag missing information and agree on secure sharing, follow-up and continued access to records.
Agree on the period and accounts first
Before gathering files, confirm the business, the month being worked on, the accounts in scope and when the agreed records should be available. Include a note about new or closed bank accounts, credit cards and payment platforms. If earlier months are incomplete, flag them rather than assuming they are included. Ask which records your bookkeeper already has access to so you can avoid duplicate submissions without overlooking a missing account.
Use a suggested records checklist
The CRA describes records as both accounting information and the documents supporting transactions, including bank statements, sales invoices and purchase receipts. Depending on your business and agreed scope, consider gathering:
- Bank and credit-card statements for each relevant account and period, with transaction exports if requested. Identify any missing pages or gaps rather than sending an incomplete statement without explanation.
- Sales invoices, cash-sales records, customer payment details, refunds and credit notes. If you sell through a payment platform, include available settlement and fee reports so the underlying activity can be compared with deposits.
- Supplier invoices, purchase receipts and payment records. Add a short explanation where the item or its business purpose is unclear, and identify any purchases paid personally by an owner.
- Lists of unpaid customer invoices and supplier bills, including known disputes, partial payments or credits. Treat these as information to discuss, not instructions to collect or pay amounts automatically.
- Existing bookkeeping reports and information about loans, equipment purchases or other unusual activity that may need clarification. Ask what supporting agreements or schedules would be helpful.
- Payroll summaries and GST/HST or BC PST summaries where applicable, plus a short list of missing documents and unresolved questions. Confirm the required detail rather than assuming every category applies to every business.
For sole proprietors and partnerships, CRA guidance says income records must identify the date, amount and source, with documents supporting income entries. It also calls for receipts or other vouchers for business purchases. Use those details to check whether your files explain the activity; this suggested handoff list is not a test of tax deductibility.
Explain transactions instead of guessing
Try a short transaction-note list with the date, amount, account and question. For example, flag a transfer between your own accounts, an owner-funded purchase or a payment covering several invoices. Avoid assigning an uncertain item a final category simply to clear the list. Where a document is missing, say what you have, what is missing and who will follow up. Do not mark missing records as resolved merely because bookkeeping has started. An open question is more useful than an unsupported explanation.
Keep the connection between documents and entries
The CRA says electronic records must provide a trail connecting supporting documents to summarized financial accounts. As a practical approach, keep invoice numbers, payment references and related reports together. For a platform sale, retain the available sales and settlement detail rather than relying only on the bank deposit. If an entry needs clarification or correction, preserve the explanation and supporting reference instead of making an unexplained change.
Check readability, access and backups
Records created electronically must remain in an electronically readable format even when you also have printouts. Do not assume that photographing a receipt or uploading it permits destruction of the paper original; CRA guidance sets conditions for replacing paper records with electronic images. As preparation steps, open a sample of your files, check that important details are legible and confirm how backups and exports will remain accessible before changing software.
You remain responsible for protecting required records and making them available to the CRA even when someone else keeps them. CRA requirements include reliable, complete records supported by documents, and proper backups for electronic records. Agreeing on who uploads, answers questions and retains access can help make those responsibilities practical.
Plan the handoff and follow-up
Consider one folder per period, clear file names and a shared list of outstanding questions. Confirm an appropriate secure sharing method before sending records. To discuss monthly bookkeeping with MH Ledger, start with a summary of your business, current process and most recent completed period. Do not send financial documents or account credentials through the general inquiry form; the records, schedule and reporting can be discussed within an agreed scope.